Monday, August 23, 2021

Section 148 Reassessment order passed in case of non-existent entity is void


Written Petition No 950 of 2020
Date of judgment/order: 09.04.2021
Related Assessment Year – 2012-13
Court: Bombay High Court

The Hon’ble Bombay High Court has in case of writ petition filed by Teleperformance Global Services Private has held that assessment order passed against a non-existent company is void.

M/s Tecnovate Esolutions Pvt Ltd (TSPL) was registered company engaged in business of providing back office services/remote data entry services for customers in and outside India. Under order dated 11.02.2011 a scheme of amalgamation of aforesaid company with M/s Intelnet Global Services Pvt ltd, was approved with effect from 01.04.2010 and since then TSPL ceased to exist. Subsequently, M/s Intelnet Global Services Pvt Ltd amalgamated with M/s Serco BPO Pvt Ltd. Thereafter there has been change in the name with effect from 11.01.2016 from M/s Secro BPO Pvt Ltd to M/s Intelnet Global Services Pvt Ltd. There has been further change in name from Intelnet Global Services Pvt Ltd to Teleperformance Global Services Pvt Ltd (TGSPL) w.e.f 12.02.2019.

Notice u/s 148 of the Act for AY 2012-13 was issued to TSPL directing to file return of income within 30 days stating that there is reason to believe that income chargeable to tax had escapement, without realising that said company was non-existent entity. In response to notice TSPL filed a letter that w.e.f 01.04.2010 TSPL has been amalgamated and since then the said company do not exist and as such there is no question of filing return of income for AY 2012-13. The then company M/s Intelnet Global Services Pvt Ltd had duly filed return of income for all the subsequent years and submitted that the above notice u/s 148 was issued on misconception and appears to be an inadvertent error. The AO without considering the reply or even the telephonic conversation passed assessment order on 31.12.2019 for AY 2012-13 under section 144 r.w.s 147 of the Act, in the name of TSPL computing taxable income of Rs. 14,50,95,452/-. Aggrieved by the order, the TSPL filed writ petition challenging the notice issued u/s 148 and assessment order passed u/s 144 r.w.s 147.

The Hon’ble Bombay High Court has observed as under;-

The Supreme Court in the case of Maruti Suzuki (supra) had considered that income, which was subject to be charged to tax for the assessment year 2012-13 was the income of erstwhile entity prior to amalgamation. Transferee had assumed liabilities of transferor company, including that of tax. The consequence of approved scheme of amalgamation was that amalgamating company had ceased to exist and on its ceasing to exist, it cannot be regarded as a person against whom assessment proceeding can be initiated. In said case before notice under Section 143(2) of the Act was issued on 26.9.2013, the scheme of amalgamation had been approved by the high court with effect from 1.4.2012. It has been observed that assessment order passed for the assessment year 2012-13 in the name of non-existing entity is a substantive illegality and would not be procedural violation of Section 292 (b) of the Act. The Supreme Court in its aforesaid decision, has quoted an extract from its decision in Saraswati Industrial Syndicate Ltd. Vs.CIT8. The Supreme Court has also referred to decision of Delhi high court in the case of CIT Vs. Spice Enfotainment Ltd.9and observed that in its decision Delhi high court had held that assessment order passed against non-existing company would be void. Such defect cannot be treated as procedural defect and mere participation of appellant would be of no effect as there is no estoppel against law. Such a defect cannot be cured by invoking provisions under section 292B.

The Supreme Court had also taken note of decision in Spice Entertainment (supra)was followed by Delhi high court in matters, viz. CIT Vs. Dimensions Apparels (P.) Ltd.10, CIT Vs. Micron Steels (P) Ltd.11; CIT Vs. Miscra India (P). Ltd.12 and in CIT Vs. Intel Technology India Ltd.13 Karnataka high court has held, if a statutory notice is issued in the name of nonexisting entity, entire assessment would be nullity in the eye of law.

The decision in the case of Maruti Suzuki (supra) would hold sway over present facts and circumstances”.


Author Bio


Qualification: CA in Practice
Company: E.A. Patil & Associates LLP
Location: Navi Mumbai, Maharashtra, India

facebook sharing button Share
twitter sharing button Tweet
email sharing button 

Tuesday, July 27, 2021

43rd GST Council Meeting Held on 28th May, 2021- Key Highlights


43rd GST Council Meeting Held on 28th May, 2021- Key Highlights

To combat the difficulties faced by the taxpayers in the light of the second wave of COVID 19 pandemic accompanied with the gradual increase in the Black, white and yellow fungus cases, the 43rd GST Council Meeting was held on 28th May, 2021. A series of recommendations were issued through the Video meet chaired by Nirmala Sitharaman.

The same are in the nature of recommendation and not effective as yet. 

We have divided the same into parts for the ease of understanding and referral:

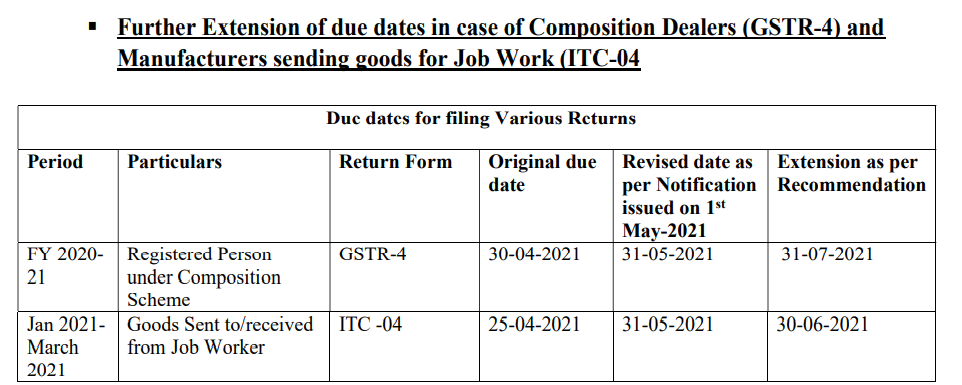
 1.     Relaxations in various due dates

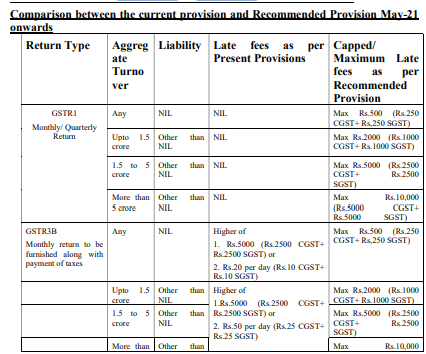
 2.     Rationalization in late fees for filing GSTR1 and GSTR3B

 3.     Cumulative availing credit as per GSTR2A for April, May and June-2021

 4.    Simplification in furnishing the mandatory requirement of Annual return and Reconciliation statement for 2020-21

 5.     Retrospective effect for charging interest on net cash liability

 6.     Relief in GST rates in case of COVID-19 related Medical Goods

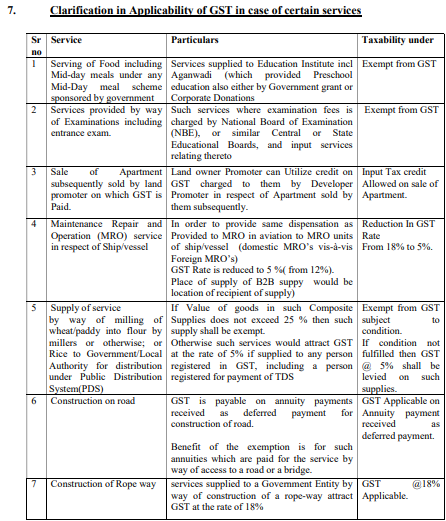
 7.     Clarification in Applicability of GST in case of certain services

 8.      Extension for time limit for completion/ compliance of any action, by any authority or by any person


3.   Cumulative Availing Credit as per GSTR2A for April, May, June-2021

           Present Provision 

The GST credit availed in a particular month cannot exceed 105% of the ITC reflected in GSTR2A of the respective month.

          Amended Provision for April, May-2021 (Notf.13/21-CGST dt.1st May, 21)

The ITC which shall be availed in the GSTR3B of April-2021 and May-2021 shall cumulatively not exceed 105% of the total ITC reflected in GSTR2A of April-2021 and May-2021.

         Recommended Provision for April, May, June-2021 

The ITC which shall be availed in the GSTR3B of April, May and June-2021 shall cumulatively not exceed 105% of the total ITC reflected in GSTR2A of April, May and June-2021.

   4.   Simplification in furnishing the mandatory requirement of Annual Return (GSTR9) and Reconciliation Statement (GSTR9C- Formerly known as GST Audit Report) for F.Y.2020-21


5.  Retrospective effect for Interest on Delayed Payment of Tax to be charged on Net Cash Liability

           Present Provision: 

         Through the Finance Bill, 2019 it was proposed that the interest on delayed payment of tax would be charged on Net Cash Liability i.e. the amount debited from the electronic cash ledger from the GST portal.

 However, there were deliberations if this was to be give retrospective effect or prospective effect.

           Recommended Provision: 

In the Finance Bill and also as per the recommendations, the interest on delayed payment of tax liability shall be levied on the Net Cash liability.

      6. Relief in GST rates in case of COVID-19 related Medical Goods

          Full exemption from GST has been recommended to be granted in case of items such as

          Medical oxygen 

          Oxygen Concentrators 

          Other oxygen storage and transportation equipment Certain Diagnostic markers test kits

         COVID vaccines

          Amphotericin B and other such items (list to be notified in due course) for the treatment of black fungus, even if imported on payment basis, for donating to the government or on recommendation of state authority to any relief agency up till 31st August, 2021.

 Initially IGST exemption was applicable only when the aforementioned goods were imported free of cost. This extension shall also be available till 31st Aug, 21.

 GST rate on Diethylcarbamazine (DEC) tablets has been recommended for reduction to 5% (from 12%) in order to support the LympahticFilarisis (an endemic) elimination programme being conducted in collaboration with WHO.

 Further relaxations have been recommended in case of repair value of re-imported goods such as sprinklers/ drip irrigation systems and other such components even if imported separately.

               8. Extension for time limit for completion/ compliance of any action, by any authority or by any person

                   The time limit for completion or compliance of any action, by any authority or by any person, which falls during the period from 15th April, 2021 to 29th June, 2021 is extended up to 30th June, 2021.


Request you to kindly go through the above and kindly note that the above provisions are yet to be notified.


                                                                                                                                                            Writer: CA Komal Allug


Monday, July 19, 2021

Recruitment and Appraisal


Team Composition

The firm has a large number of employees consisting of Chartered Accountants, students pursuing Chartered Accountancy course and Company Secretary, MBA and Graduate in accounting. Our services covers compliances and assurance as per the provisions of the Company Law, Income Tax Law and other laws which influence financials directly.

Team Training

EAP takes various initiatives for the training of employees which are relevant to the execution of assignments including wide areas such as recent amendments/changes in the Acts relating to direct and indirect tax, new methods/processes for execution of works, advance excel skills.M

Our training also covers guidance on handling of Valuation of companies, Mergers and Acquisitions (M&A), Consolidation of global operations as per law, Foreign exchange Management Act (FEMA) related topics. We also focus on the softs skills of employees

The training is conducted in-house and also we invite professionals having required technical knowledge. These trainings are mandatory based on the employee skill requirement.

Team Preparedness for Assignments

The employees are provided with formal training at the firm covering various subjects and their practical implementation on the assignments. In-house periodical training of employees helps them to keep pace with the changes in the curriculum. Employees work is reviewed by the managers who work closely on the assignments.

Employee Quality review

EAP has qualified Managers who plan assignments and perform quality. The firm constantly reviews its checklists to ensure the effectiveness of its processes. Internal Quality review team ensures quality adheres to the standards set. These standards are benchmarked to the best practices in the industry which includes the Accounting and auditing guidelines and standards, Risk Assessment approaches.

Employee appraisal

The annual performance appraisals of the employees are performed by the HR team and actively participated by the partners. The appraisals are scientific and based on formal procedures.

Land Mark Judgement: No section 14A disallowance if assessee had sufficient interest free own fund

  Case Law Details Case Name :  South Indian Bank Limited Vs CIT (Supreme Court of India) Appeal Number : Date of Judgement/Order : Related ...